
which crypto card should you actually get
 Available in US
A crypto card is a Visa or Mastercard that spends the balance of a crypto wallet or app at the till or online. The simplest way to think about it is as a prepaid card with a crypto top-up rail: you load it from a wallet or exchange, the provider converts your coins at the moment of payment, and the merchant receives dollars or euros as if the card were a normal bank card. Some cards are self-custody, so the coins never leave your wallet until you tap; others are custodial, and the coins sit on the provider’s books until you spend.
The information below is current as of October 28, 2026.
Choosing one is not just about rewards. It is about whether you can get the card in the first place, what it costs you to keep, what happens when things go wrong, and whether the card actually works in the shops and apps where you spend. I have gone through every card reviewed on this site, applied a fixed scoring method, and ranked the top fifteen. The verdict and the table are the backbone of the page; the rest of the article is there to help you decide which of those cards is right for your situation.
the verdict: which crypto card is best and for whom
If you only have a minute, this is what the numbers say. The top fifteen out of every card on the site, in order, are these. The right card for you depends on which of these problems you most want solved.
| Rank | Card | Total score | Who it suits |
|---|---|---|---|
| 1 | Morse | 7.5 / 10 | Spending stablecoin balances abroad with zero FX markup |
| 2 | MetaMask | 7.1 / 10 | Self-custody wallet users in Europe and Latin America |
| 3 | RedotPay | 6.9 / 10 | Crypto holders outside the restricted list who want virtual or plastic |
| 4 | Wallbit | 6.7 / 10 | Dollar savers wanting a US account and Visa funded by USDC |
| 5 | Card.fi | 6.6 / 10 | Spending many different coins on a virtual or metal card |
| 6 | Stella | 6.5 / 10 | Crypto holders wanting Visa with ATM and Alipay support |
| 7 | Coinbase | 6.4 / 10 | US residents who spend crypto and earn rewards |
| 8 | Wasabi | 6.4 / 10 | Businesses and users wanting stablecoin virtual and physical cards |
| 9 | MSX | 6.4 / 10 | MSX platform users wanting a Visa card for their crypto |
| 10 | KAST | 6.1 / 10 | Stablecoin holders spending USD balances across many networks |
| 11 | Telecard | 6.1 / 10 | Telegram users wanting an instant virtual card with USDT |
| 12 | UNi | 6.1 / 10 | Multi-currency spenders wanting rewards up to 3% |
| 13 | Bybit | 6.0 / 10 | Exchange users in Georgia, Kazakhstan, Australia and Latin America |
| 14 | OkiCard | 6.0 / 10 | Users wanting a no-KYC card funded in USDT |
| 15 | TokenPocket | 5.8 / 10 | TokenPocket users spending crypto in Europe and Asia-Pacific |
What that table does not show is that different cards solve different problems. Here is the short version, broken down by the question you are most likely asking.
- Lowest costs: Morse (cost 8 / 10). Conversion has no markup and card payments are free; the catch is that the issuer and monthly fees are not publicly listed.
- Best top-up options: Card.fi (funding 9 / 10). It accepts 32 coins across five networks, including USDT, USDC, ETH, BNB, SOL and KAANCH.
- Most reliable: Morse (reliability 8 / 10). The issuer is Lead Bank and the platform is Avian Labs, registered as an MSB in the US and authorised under MiCA in the Netherlands; no official incidents or complaints are on file.
- Best for everyday use: Card.fi (convenience 10 / 10). Virtual, physical and metal cards, with Apple Pay and Google Pay on the physical cards, plus ATM withdrawals.
- Easiest to get: Card.fi (availability 9 / 10). Cards ship to more than 200 countries, with only sanctioned jurisdictions excluded.
If you want the deepest answer, the next section walks through the top fifteen cards one by one. If you have a specific problem to solve, skip to the tasks section. If you are still deciding whether a crypto card is for you at all, the choose, method and risks sections explain how the scores are built and what can go wrong.
the top crypto cards, one by one
What follows is what I checked, what the card costs, who it is really for, and the small print that often decides whether a card is usable for you.
1. Morse — 7.5 / 10
Morse sits at the top because the conversion is clean: there is no FX markup on card payments, no transaction fee, and the rate is the live Visa rate. It is the right card if you hold USDC, USDG or EURC and you want to spend them abroad without losing anything to spread.
- Who can get it: 7 / 10. The app works in 140+ countries and supports local add and withdraw in 70+, but the card itself is only available in some of them, and the list is in the app, not on the website. Closed-beta countries that need an invite code include Australia, New Zealand, Singapore, Hong Kong SAR China, Japan, Switzerland, the United Kingdom, Türkiye, Thailand, Serbia, Cape Verde, Guernsey, Isle of Man, Jersey, American Samoa and Western Sahara. Sanctioned countries are closed.
- Cost: 8 / 10. The card page does not list an issuance or monthly fee; it only says “Fees may apply” and points to the Cardholder Agreement. Spending is free, currency conversion has no markup, and “paying with the Morse Card, online and contactless, is free.”
- Top-up options: 8 / 10. Deposits of USDC, USDG and EURC via Solana are free; Bitcoin, USDT, Ethereum and other tokens are accepted on other networks with a fee. The wallet is self-custodial, so you keep the keys.
- Reliability and complaints: 8 / 10. The issuer is Lead Bank, and the platform Avian Labs is an MSB in the US and authorised under MiCA in the Netherlands. There are no public incidents or complaints.
- Everyday use: 6 / 10. Apple Pay and Google Pay are supported, but the card is virtual-only and ATM withdrawals are not supported.
- Audience: spending stablecoin balances abroad with zero FX markup.
Morse is the right pick if you already hold USDC and you are travelling or shopping online in a foreign currency. It is not the right pick if you want a physical card or to pull cash from an ATM.
2. MetaMask — 7.1 / 10
The MetaMask Card is the option for people who already keep their crypto in MetaMask and want a card that draws on that wallet directly. The headline numbers are good: the virtual card is free, there is no annual or monthly fee, and the Metal tier at $199 a year is one of the more expensive choices in the category but offers a 3% mUSD cashback capped at $10,000 of spend.
- Who can get it: 7 / 10. Sign-up is open in 45 countries, including most of the EU, the UK, Canada, Brazil, Argentina, Mexico and Uruguay. Sign-ups from the US and the UK are temporarily closed. Proof of residency is required; the rules are about residence, not citizenship.
- Cost: 8 / 10. Virtual card is free; Metal is $199 a year. There is a “minimal fee” on each transaction, the amount is not on the main pages; there is no foreign transaction fee; the Mastercard rate is used.
- Top-up options: 8 / 10. Spends directly from the connected wallet on Linea, Base, Monad and Solana. Tokens include mUSD, wETH, EURe, GBPe, USDC and USDT. A Solana-only wallet cannot withdraw credit.
- Reliability and complaints: 4 / 10. Issuer is Monavate; the card provider is Crypto Life. There are reports of refunds landing as “Credits” rather than cash, tickets going silent, and cards being frozen. Unofficial reports (cryptocards.so, 2026) describe a physical card arriving about a month after order.
- Everyday use: 9 / 10. Virtual card issued instantly, Metal card available after, Apple Pay and Google Pay supported, ATM withdrawals up to $1,000 a day on Virtual and $5,000 on Metal. Free ATM allowance “up to $1,200 a month”, though the tier is not clearly stated.
- Audience: self-custody wallet users in Europe and Latin America.
MetaMask Card is the right pick if your funds are already on MetaMask and you want a card that does not require you to trust a custodian. It is the wrong pick if ATM access and instant dispute resolution are your priority, because the support track record is weak.
3. RedotPay — 6.9 / 10
RedotPay is a broad-availability Visa with virtual and physical options and a published fee table. It loses points because the issuer is not named and the platform sits behind a “BIN Sponsor”, and the user base reports freezes tied to KYC and source-of-funds reviews.
- Who can get it: 8 / 10. The service says it has more than nine million users. Forty-seven places are on the card-issuance exclusion list (effective 28 August 2026), including India, Indonesia, Morocco, Nepal, Singapore, Turkey and a long list of sanctioned jurisdictions; the rest of the world is open.
- Cost: 6 / 10. Virtual card application is $10.00, physical card application is $100.00 (non-refundable once paid). Account maintenance is free. There is a 1.00% transaction fee and a 1.20% non-default-currency fee; ATM withdrawals are 2% (USD card) up to $10,000 a month, 3% above; HKD card 2.00%.
- Top-up options: 8 / 10. On-chain crypto deposit or buy-crypto-with-card in the app, with ETH, USDC and USDT supported (depends on region). USDT-TRC20 minimum deposit 1 USDT after network fees; deposit to card balance is free. Each asset is accepted only on the networks shown on the deposit page, and RedotPay may change them.
- Reliability and complaints: 4 / 10. The issuer is hidden behind a BIN sponsor, and the programme manager is Redotpay Technology Pte. Ltd. The Trustpilot page has 778 reviews and a recurring pattern of freezes tied to KYC and source-of-funds checks.
- Everyday use: 9 / 10. Virtual and physical, Apple Pay and Google Pay, ATM worldwide.
- Audience: crypto holders outside the restricted list who want virtual or plastic.
RedotPay is the right pick if you want a card with a published fee table, you are outside the 47-place restricted list, and you accept the cost of the application fees. It is the wrong pick if the source of your funds is complicated, because KYC reviews can freeze the account.
4. Wallbit — 6.7 / 10
Wallbit sells itself as a US-issued Visa that runs on a stablecoin balance. The interesting twist is the Account Details feature, which gives US, EUR, MXN, COP and BRL rails, so you can pay local bills in local currency from a USDC balance.
- Who can get it: 8 / 10. Closed to residents of Belarus, mainland China, North Korea, Cuba, India, Iraq, Iran, Israel, Myanmar, Nepal, Nicaragua, Russia, Syria, Turkey, Ukraine, Venezuela and Vietnam. FATF grey-list countries are reviewed case by case.
- Cost: 7 / 10. Virtual card issuance is $5 one-time; no maintenance fee. Card use in USD is free on all plans; in foreign currency, the fee is the Visa rate plus 2%. ATM withdrawals are 1% with a $5 minimum plus 1% for non-USD; the per-transaction limit is $250.
- Top-up options: 6 / 10. USDC and USDT can be deposited into the USD account free at 1:1; USD, EUR, SEPA, SWIFT and FedNow deposits are also supported. The networks for the stablecoin deposits are not named.
- Reliability and complaints: 5 / 10. The parent is Wallbit LLC with US-registered partners; SOC 2 Type I and II audited. The card issuer is not named. Trustpilot score is 4.0 from 69 reviews, with reports of accounts being closed after approval in January 2026 and unresponsive support.
- Everyday use: 7 / 10. Virtual Visa, Apple Pay and Google Pay; ATM withdrawals are possible only through contactless (NFC) on a phone wallet; the per-transaction limit is $250. A physical card is “coming soon”.
- Audience: dollar savers wanting a US account and Visa funded by USDC.
Wallbit is the right pick if you hold USDC and you want a US account, a US billing address, and a clean USD card. It is the wrong pick if you live in any of the 17 excluded countries, or if you need a physical card today.
5. Card.fi — 6.6 / 10
Card.fi is the broadest in the top fifteen for funding: 32 coins across five networks. It also has the strongest everyday-use score in the table, because the platform offers virtual, physical and metal cards, all of which can be added to Apple Pay and Google Pay, and the physical and metal cards support ATM withdrawals.
- Who can get it: 9 / 10. Cards ship to 200+ countries. The terms only bar residents of, or orders from, a country under sanctions that would prohibit the service.
- Cost: 2 / 10. Virtual Classic is $49 and Virtual Premium is $249, both one-time. There is no monthly, annual, inactivity or minimum-balance fee. Top-up fee is 1.5% plus $1.00 on Classic and 1% on Premium. FX fee is 3.5% on Classic and 2.5% on Premium.
- Top-up options: 9 / 10. 32 coins across Ethereum, Base, BNB Chain, Solana and Kaanch, including USDT, USDC, ETH, BNB, SOL and KAANCH. Each card has a dedicated deposit address. Wrong-chain deposits are at risk of permanent loss.
- Reliability and complaints: 5 / 10. The trading name is Kaanch Limited, Hong Kong. Cards are issued by On5 Card Network; licences are not named. The balance is custodial — held as a debt of the company. No complaint pages were found.
- Everyday use: 10 / 10. Virtual, physical and metal cards. Each physical order includes a virtual card. Apple Pay and Google Pay supported. Blocked categories include crypto, ATMs, cash, quasi-cash, stored-value loads, remittances, financial institutions, securities brokers, telemarketing, dating, massage, betting, regional gambling, and political or religious organisations.
- Audience: spending many different coins on a virtual or metal card.
Card.fi is the right pick if you want to spend a wide mix of coins and you want the strongest set of physical and metal options. It is the wrong pick if a 3.5% FX fee on the Classic tier is a deal-breaker, or if the missing licence information is a problem for you.
6. Stella — 6.5 / 10
Stella is a Visa card with Alipay and WeChat Pay support, which is rare in the category. Most facts about it are not on the official site, so the country list and the fee schedule come from third-party sources and are not confirmed by the card itself.
- Who can get it: 7 / 10. The official site does not publish country lists. Unofficial sources (CryptoCardHub, August 2026) say the card is available in 57 countries including the US, UK, Singapore and India, and restricted in 49 including Russia, Belarus, Ukraine, Iran, Iraq, Syria, North Korea, Cuba, Venezuela and South Africa. The terms only bar users under sanctions programmes.
- Cost: 5 / 10. The official site does not publish fees. Unofficial sources: no annual fee; virtual card application fee shown in the app only (a user complaint cites $30); physical card free after a $20,000 top-up, otherwise a delivery fee.
- Top-up options: 9 / 10. Official: deposit crypto into the account, which automatically tops up the card. Unofficial: BTC, ETH, USDT and USDC on ERC-20, TRON, BNB Smart Chain, Polygon, Arbitrum One and Optimism.
- Reliability and complaints: 4 / 10. Stella Global Services Limited (BVI); the issuer is not named; licences are not named. There are user reports of accounts being frozen with funds not returned. Unofficial Trustpilot score 3.2 from one review.
- Everyday use: 9 / 10. Virtual and physical Visa, ATM, Google Pay, Alipay and WeChat Pay. Unofficial: Apple Pay also supported.
- Audience: crypto holders wanting Visa with ATM and Alipay support.
Stella is the right pick if Alipay or WeChat Pay is part of your spending and you are in one of the 57 listed countries. It is the wrong pick if you need a fee schedule that is on the official site rather than in a third-party review.
7. Coinbase — 6.4 / 10
The Coinbase Card is the cleanest option for US residents: a Visa prepaid debit, no spending fees, no annual fee, and zero Coinbase ATM fees. The catch is that it is US-only, and Hawaii is excluded.
- Who can get it: 4 / 10. Available in all US states except Hawaii. No other countries.
- Cost: 8 / 10. “Zero spending fees and no annual fees.” ATM withdrawals cost $0 from Coinbase, though the ATM operator may charge. International transactions have 0% on the issuer side, but Coinbase’s spread applies when it converts crypto to USD.
- Top-up options: 4 / 10. Linked bank account or part of a paycheck, free. The crypto balance on Coinbase converts to USD at the moment of payment. Specific coins and networks are not listed on the card pages.
- Reliability and complaints: 7 / 10. Issuer Pathward, N.A., Member FDIC; programme runs on Marqeta. Coinbase’s overall Trustpilot score is 4.0/5 from 23,282 reviews, with recurring complaints about account blocks and slow support.
- Everyday use: 9 / 10. Virtual or physical Visa prepaid, ATM, Apple Pay and Google Pay (unofficial).
- Audience: US residents who spend crypto and earn rewards.
Coinbase Card is the right pick if you live in the US outside Hawaii, your crypto is already on Coinbase, and you want a fee-free card with optional crypto rewards. It is the wrong pick for everyone else.
8. Wasabi — 6.4 / 10
Wasabi is a stablecoin-funded Visa or Mastercard with virtual and physical options. The terms are short on amounts, and the programme manager (Wasabi Ltd) explicitly says it is “not a bank or custodians”.
- Who can get it: 9 / 10. The platform’s starting data says 200+ countries and regions. The terms bar users in any prohibited or sanctioned jurisdiction. There is no published country list.
- Cost: 5 / 10. The terms list the fee types (issuance, FX, cross-border, ATM, chargeback handling, replacement) but do not give amounts. No monthly fee is published.
- Top-up options: 6 / 10. Stablecoin-funded (“Spend with Stablecoin”). Coins and networks are not stated on the official pages; starting data points to USDT on TRC-20 and BEP-20.
- Reliability and complaints: 4 / 10. Wasabi Ltd, “not bank or custodians”; issuer and licences are not named. One Trustpilot review from 8 July 2026 mentions high starter payments and card limits.
- Everyday use: 8 / 10. Virtual card with instant Apple Pay binding, physical card that can be added to Apple Pay, ATM worldwide. Google Pay is not stated.
- Audience: businesses and users wanting stablecoin virtual and physical cards.
Wasabi is the right pick if you want a stablecoin-funded card with virtual and physical options, and you accept the lack of published fees. It is the wrong pick if you need a published fee schedule before you sign up.
9. MSX — 6.4 / 10
MSX is the card for users of the MSX (Maitong) platform. Most of the facts here are from unofficial sources, including a sponsored article and a third-party crypto news site, and are not confirmed by the card issuer.
- Who can get it: 8 / 10. Unofficial: global, with ATM coverage in multiple countries and regions outside Mainland China and OFAC-sanctioned areas. Starting data says the MSX platform is closed to the US, Canada and Hong Kong.
- Cost: 7 / 10. Unofficial: zero annual, top-up and payment fees for an initial promotional period; later fees are not disclosed. FX fee is not stated.
- Top-up options: 5 / 10. Unofficial: spending is funded from crypto assets held on the MSX platform; starting data says stablecoin top-up (USDT, USDC) from the MSX account, converted at point of sale.
- Reliability and complaints: 5 / 10. Unofficial: MSX is operated by Maitong, with MSB registrations in FinCEN and Canada. Issuer is not named. No complaints found.
- Everyday use: 6 / 10. Unofficial: physical card on the Visa network for online and offline use, Google Pay contactless, ATM in multiple regions. Apple Pay is not stated.
- Audience: MSX platform users wanting a Visa card for their crypto.
MSX is the right pick if you already keep assets on MSX and you want to spend them on a Visa without leaving the platform. It is the wrong pick if you want a published fee schedule.
10. KAST — 6.1 / 10
KAST is a stablecoin-funded Visa that runs in tiers (Standard, Premium, Private) and offers a metal Visa Infinite on the higher tiers. The standard tier is the cheapest published option in the top fifteen, with zero annual fee and zero top-up fee on stablecoins.
- Who can get it: 5 / 10. The country list is shown at KYC and not published. The Visa is accepted in 170+ countries (the platform’s claim). KYC can be blocked if the applicant’s country is not on the list, even if they live in a supported country but hold an ID from a restricted region.
- Cost: 6 / 10. Standard tier: $0 a year, physical card $0 plus $40 delivery, extra virtual card $2. Premium: $1,000 a year. Private: $10,000 a year (billed annually upfront). Stablecoin top-up 0%, USD spending 0%, transaction fee 0%, Apple/Google Pay 0%. Non-USD FX fee 0.5% to 1.75%. ATM: $3 flat plus 2%. Inactivity fee $1 a month after 12 months.
- Top-up options: 9 / 10. USDT, USDC, PYUSD and RLUSD. USDT and USDC on Ethereum, Solana, Polygon, Arbitrum and TRON. The terms say “currently USDT and USDC” but the app lists PYUSD and RLUSD — the documents conflict.
- Reliability and complaints: 3 / 10. Issuer not named; no licences named; structure is KAST Tech in Anjouan (Comoros). Trustpilot 2.5 to 2.7, with complaints about frozen accounts and repeated document requests.
- Everyday use: 9 / 10. Virtual and physical, Apple Pay and Google Pay, ATM on the Visa network. Up to 10 cards per user.
- Audience: stablecoin holders spending USD balances across many networks.
KAST is the right pick if you hold stablecoins on multiple networks and you want a tiered product with cashback. It is the wrong pick if you want a clear paper trail, because the issuer and licence information is not public.
11. Telecard — 6.1 / 10
Telecard is a Telegram-bot-issued virtual Mastercard, sold for “instant” use with USDT on Tron or Ethereum. There is no physical card and no ATM access.
- Who can get it: 8 / 10. Works in more than 150 countries where Mastercard is accepted. Identity check is available in most major regions. The terms only bar users “blocked or sanctioned by the United States Government, including OFAC”.
- Cost: 6 / 10. Standard plan is $5 one-time; VIP is $49 setup then $19 a month. Conversion 1.5% on non-USD payments. Gas fee 0.5 USDT per successful card transaction. There is a $99 minimum deposit to activate, but the platform says it is “NOT a fee” — the funds stay in the wallet.
- Top-up options: 7 / 10. USDT on Tron (TRC-20) and Ethereum (ERC-20); USDC on Ethereum. Bank transfers are “coming soon”.
- Reliability and complaints: 3 / 10. The legal entity, jurisdiction, issuer and licences are not named. Funds sit in a custodial account on the platform. No reviews found.
- Everyday use: 6 / 10. Instant virtual Mastercard, Apple Pay and Google Pay; no physical card; no ATM.
- Audience: Telegram users wanting an instant virtual card with USDT.
Telecard is the right pick if you are inside Telegram and you want a card in the next five minutes, paid for with USDT on Tron. It is the wrong pick if you need a physical card, ATM access, or a published issuer name.
12. UNi — 6.1 / 10
UNi is a multicurrency Mastercard with a 12+ currency wallet and cashback of up to 3% on spend. The card has a published “no annual fee, no foreign transaction fee” line but most other facts are not on the public pages.
- Who can get it: 5 / 10. The list of countries is not published; the platform says it is “subject to jurisdictional limitations”.
- Cost: 8 / 10. No annual fee, no foreign transaction fee, conversion at “live OTC (Over-the-Counter) rates”. Issuance fee is not stated.
- Top-up options: 5 / 10. The top-up method is not disclosed. The wallet holds 12+ currencies; the card spends from the UNi.Global balance.
- Reliability and complaints: 6 / 10. UNI.Global is described as AUSTRAC-regulated, with offices in Sydney, Auckland, Hong Kong and Taipei. Issuer not named. No complaints found.
- Everyday use: 6 / 10. Multicurrency Mastercard, Apple Pay and Google Pay, in-app card freeze. Card type and ATM access are not stated.
- Audience: multi-currency spenders wanting rewards up to 3%.
UNi is the right pick if you want a multicurrency wallet with a Mastercard and you do not need ATM access. It is the wrong pick if you need to know the issuer, the issuance fee, or the supported countries before you sign up.
13. Bybit — 6.0 / 10
The Bybit Card is a Mastercard or Visa tied to the Bybit exchange, available in a defined set of regions, with a credit-card option in some of them. EEA customers are explicitly prohibited.
- Who can get it: 6 / 10. Card regions: Argentina, AIFC (Kazakhstan), Georgia, Kazakhstan, Australia, Mexico, Brazil, Peru, Asia Pacific. “This product is not meant for European Economic Area customers. All European Economic Area customer participation is strictly prohibited.” Bybit’s fiat-service restricted list includes Belarus, Russia, Serbia, China and the US.
- Cost: 5 / 10. Virtual card issuance is free in all regions until further notice. Physical card: 29.99 USDT in Georgia and Kazakhstan (AIFC), 29.99 USD in Australia, 5 USDT in Asia Pacific, 5 USD/USDT in Argentina, free in Brazil and Mexico. Crypto conversion 0.9% (0.5% in Argentina, not supported in Peru). FX 2% on top of the network rate (Australia, Asia Pacific, Georgia, Mexico); 7% in Argentina; 1.5% in Brazil; 1% in Peru. ATM 2% after the first $100 a month.
- Top-up options: 7 / 10. The card has no balance of its own; it draws on the Funding Account and the Flexible Easy Earn balance, fiat first, then crypto at the One-Click Sell rate. Supported cryptos: BTC, ETH, XRP, USDT, USDC, GRAM. Default priority USDT > USDC > GRAM > BTC > ETH > XRP, reorderable.
- Reliability and complaints: 4 / 10. Issuer by region is not named. Bybit’s Trustpilot score is 2.5. There are reports of cards being cancelled after the 2026 programme change. Account restriction stops the card.
- Everyday use: 9 / 10. Virtual and physical, Apple Pay, Google Pay and Samsung Pay (Australia); Apple Pay and Google Pay in Georgia, Kazakhstan, AIFC, Argentina, Brazil and Peru; Google Pay only in Asia Pacific and Mexico. ATM available. Physical card is issued after the virtual.
- Audience: exchange users in Georgia, Kazakhstan, Australia and Latin America.
Bybit Card is the right pick if you keep funds on the Bybit exchange and you live in one of the listed regions. It is the wrong pick if you are in the EEA or in any of the restricted regions, and the support track record is a concern.
14. OkiCard — 6.0 / 10
OkiCard is a virtual card funded by USDT, marketed as no-KYC and “no geo-blocking based on your passport”, with the actual restriction being on sanctioned jurisdictions only.
- Who can get it: 8 / 10. Marketed as 150+ countries (some pages say 200+). “No geo-blocking based on your passport”; users must confirm they are not in a sanctioned jurisdiction.
- Cost: 5 / 10. Issuance $0, maintenance $0, starting price $15 for the virtual card. Load fee 3%. USD transaction fee 0%. FX fee not stated. Initial deposit 100 USDT.
- Top-up options: 8 / 10. USDT on BSC (BEP-20), Ethereum (ERC-20), Tron (TRC-20) and Solana (SPL). USDC “soon”. BTC and altcoins “coming soon”.
- Reliability and complaints: 3 / 10. The legal entity is not named; the jurisdiction field in the terms is “[Insert Jurisdiction]”; issuer not named. No reviews found.
- Everyday use: 6 / 10. Virtual card in 60 seconds, Apple Pay and Google Pay. A physical card is mentioned without details. ATM is not stated.
- Audience: users wanting a no-KYC card funded in USDT.
OkiCard is the right pick if you want a quick virtual card and you only hold USDT. It is the wrong pick if a published legal entity and a published jurisdiction matter to you, or if you need a physical card or ATM access.
15. TokenPocket — 5.8 / 10
The TokenPocket (TP) Card runs on the Fiat24 stack, with a virtual Mastercard or Visa debit tied to an Arbitrum wallet. The published fee is a 1% crypto deposit fee that “will later be refunded to users through rewards”.
- Who can get it: 7 / 10. Visa debit for a list of European countries (Germany, France, Spain, Switzerland, etc.). Mastercard debit for Australia, Canada, Hong Kong, Japan, Taiwan, New Zealand, Singapore, South Korea and the UK. Americas “planned for Q2 2025”.
- Cost: 7 / 10. The NFT creation fee is partly covered by TokenPocket; the user pays a “small portion”, amount not stated. “Apart from these, TP Card does not charge any additional fees.” FX fee not stated; extra fees can come from inter-institution settlement.
- Top-up options: 4 / 10. Crypto deposits from the TokenPocket wallet; specific coins and networks not in the FAQ. The card runs on Arbitrum. Balances are held in EUR24 and USD24.
- Reliability and complaints: 4 / 10. The issuer is not named in the FAQ; support is via Fiat24. Trustpilot for Fiat24 is 2.2 from 8 reviews, all one star, with complaints about silent support and delayed funds.
- Everyday use: 6 / 10. Apple Pay, Google Pay, Samsung Pay, Alipay and WeChat Pay. Cards are virtual. No physical card or ATM access mentioned.
- Audience: TokenPocket users spending crypto in Europe and Asia-Pacific.
TokenPocket Card is the right pick if your wallet is already TokenPocket and you want to spend from it on Alipay or WeChat Pay. It is the wrong pick if you need a physical card or ATM access.
the best cards for each task
Different problems, different cards. Here are the cards I would shortlist if I had a specific job to do.
topped up with USDT
The cheapest USDT top-up in the top fifteen is MetaMask, which spends from the connected wallet with no extra fee. Morse is the next best, with free USDC, USDG and EURC deposits on Solana and a zero-markup conversion. RedotPay is third, with USDT-TRC20 deposits from 1 USDT after network fees, free of card-side deposit fees.
with Apple Pay or Google Pay
Apple Pay and Google Pay are now table-stakes. The cleanest is Morse, with both supported and no merchant restrictions stated. MetaMask supports both on virtual and metal cards. RedotPay lists Apple Pay and Google Pay integration on the virtual card, with the caveat that individual merchants may decline prepaid or crypto cards.
with cashback
Cashback is the differentiator that matters most to frequent spenders. Card.fi pays 0.8% to 2% on card spend (1.2% to 2% on Metal) with a 10% headline at coffee shops capped at 10 USDT a month. KAST pays 1.5% to 3% in USD on the standard, premium and private tiers, with KAST Points on top. UNi advertises spend-to-earn rewards up to 3%. The catch on all three is that the headline rate is on a tier with a monthly cap, and the lower tier usually pays less than 1%.
virtual cards for online payments and subscriptions
A virtual-only card is the right shape for online subscriptions and ad spend, because the card cannot be skimmed at a terminal. Wallbit ships a US-issued Platinum Visa in seconds, pays in USD and supports Apple Pay and Google Pay. Card.fi ships virtual Classic and Premium, with a fee schedule that is published only after a one-time issuance fee. Stella is a third option if you also want Alipay and WeChat Pay; its country list is unofficial, so the card is only safe if your country is on it.
how to choose a crypto card for yourself
The card you pick is shaped by three questions, in this order: where you live, what coin you want to spend, and how you actually pay. The card that wins on a scoreboard can still be the wrong card for you if any of those three answers is wrong.
Where you live is the first filter. Every card on this site has a country or region list, and most have a sanctioned-jurisdiction clause. The list is sometimes on the card page, sometimes in the app at KYC, and sometimes not published at all. If your country is not on the list, the card is not for you, no matter how good it looks. Examples: the MetaMask Card lists 45 supported countries, and US and UK sign-ups are temporarily closed; the Bybit Card is restricted to a defined set of regions and explicitly bars EEA customers; RedotPay excludes 47 places; Wallbit excludes 17.
What coin you want to spend is the second filter. USDC and USDT are the easiest to top up because they are the stablecoins every provider accepts. Cards that accept more coins — Card.fi (32 across five networks), KAST (USDT, USDC, PYUSD, RLUSD), OkiCard (USDT on four networks) — give you more flexibility but often charge a top-up fee for the privilege. Self-custody cards (Morse, MetaMask) let the funds stay in your own wallet until payment; custodial cards (KAST, Card.fi) hold the funds on the provider’s books, which adds counterparty risk.
How you actually pay is the third filter. If you tap your phone, you want Apple Pay and Google Pay; if you shop online, you want a virtual card with a clean BIN; if you travel, you want a low FX fee and a card that works in the country you visit. A few specifics to look for:
- FX fee: a 0% FX markup (Morse) is rare. Most cards charge 1% to 3.5%. A card with a 0% transaction fee can still have a spread on the conversion.
- ATM: many top cards do not support ATM withdrawals (Morse, Telecard, OkiCard, TokenPocket). If you need cash, check the ATM section first.
- Card network: Visa and Mastercard behave the same at most merchants, but AVS and 3-D Secure work better on cards issued in the country of the merchant.
- Cashback: published rates are usually capped. Look for the monthly cap and the spend threshold, not the headline.
- KYC: some cards are KYC-light (OkiCard, Card.fi) but that comes with a higher counterparty risk and a thinner paper trail.
A useful check before you sign up: open the card’s terms and look for three things — the issuer, the licence, and the country list. If the issuer is a “BIN Sponsor” and the licence is not named, you are trusting a programme manager that may not have a direct banking relationship.
how the cards are scored
Every card on the site is scored on the same five criteria. The weights are fixed, the order is fixed, and the score is out of 10.
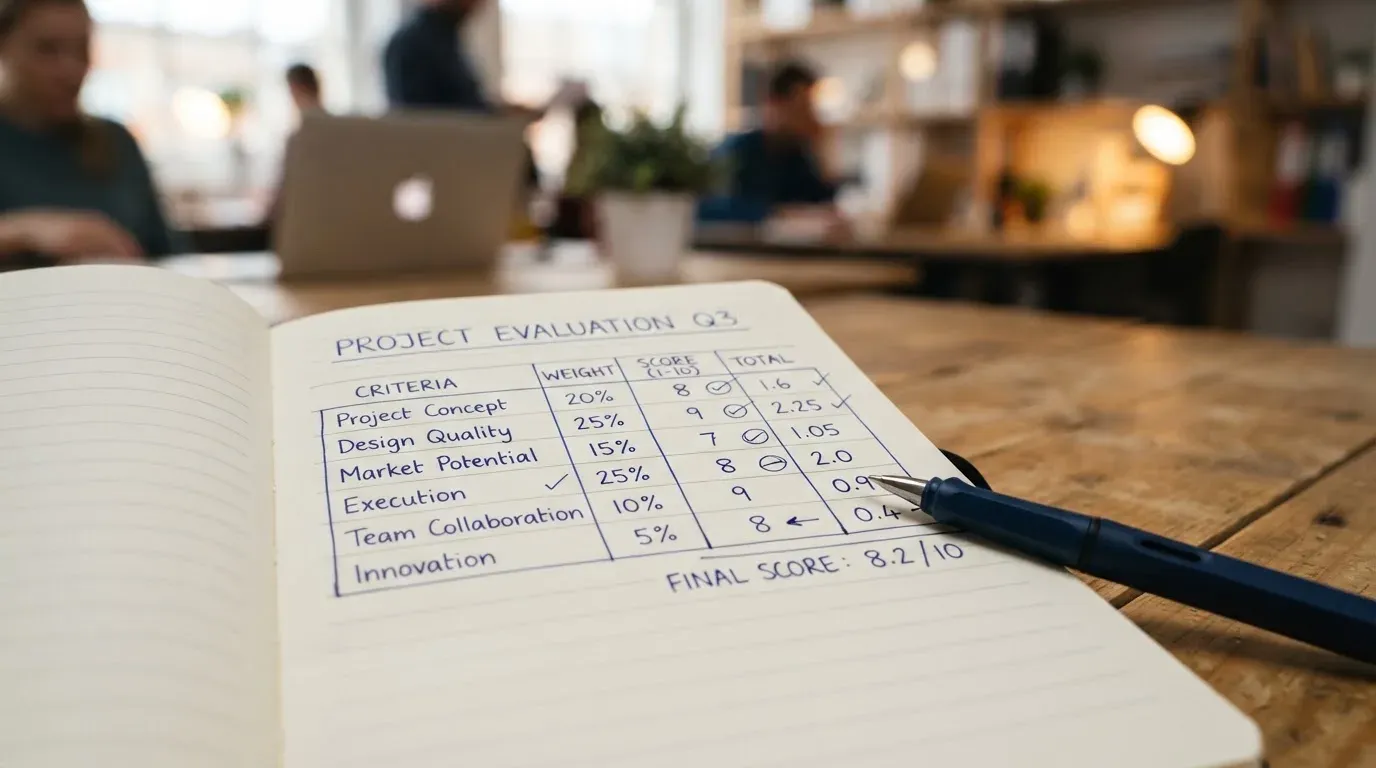
- Who can get it: 25%. Country and region support, residency rules, sanctioned-jurisdiction clauses and the practical reality of getting through KYC.
- Cost: 25%. Issuance, monthly, annual, transaction, FX, ATM and top-up fees, with attention to the published fee table and any “fees may apply” wording.
- Top-up options: 15%. The number of supported coins, the number of supported networks, the deposit fee, the spread on conversion, and whether the wallet is self-custodial or custodial.
- Reliability and complaints: 20%. The identity of the issuer, the licences held, the trust registrations, the track record of incidents, the Trustpilot or equivalent review, and the consistency between official and third-party sources.
- Everyday use: 15%. Virtual and physical availability, Apple Pay and Google Pay, ATM access, blocked merchant categories, and the realistic experience of paying with the card at a till or online.
The five scores are weighted, summed and rounded to one decimal place. The total is what you see in the table. The quick-pick categories at the top of the page use the single highest score in the relevant criterion, not a new total.
what can go wrong with any crypto card
A crypto card is a payment product on top of a crypto balance, and either layer can fail. The pattern I see across the cards on this site falls into a small number of categories.
KYC and source-of-funds freezes. The single most common complaint is the account being frozen because KYC could not be completed, or because the platform could not verify the source of the funds. RedotPay, Wallbit, KAST and MetaMask all show this pattern in their reviews. Once frozen, the funds are usually recoverable only after a long document chase, and sometimes not at all.
Issuer and programme changes. The card you sign up for is the card the issuer chooses to keep. Visa itself has terminated programmes (FTX in November 2022) and has suspended issuers (WaveCrest in Europe in 2018), and a single-source 2026 closure (new loads ended 8 July 2026, spending stopped 8 August 2026) is a reminder that the underlying programme can wind down. When it does, you usually get a notice period, then a stop on spending, then a request to withdraw the balance.
Sanctions and country exclusions. Sanctions are enforced by the card network, the issuer and the programme manager, often all three. If your country becomes sanctioned, or your country was always on the list, the card stops working. The exclusion lists are not always public, and the terms usually put the burden on the user to check.
Stablecoin and network risk. Stablecoins can depeg (TerraUSD in May 2022, USDC briefly in March 2023), and a stablecoin sent on the wrong network can be lost. Circle stopped supporting USDC on Tron in February 2024, so “USDC over TRC20” is not a native option. Tether has frozen wallets on the OFAC sanctions list, so stablecoins are not censorship-proof.
Counterparty risk on custodial balances. Custodial platforms have a record of failures: Mt. Gox, Coincheck, Ronin. Funds held with a custodian are not bank deposits and are not covered by deposit guarantee schemes; in the EU, EMIs must safeguard customer funds, but that is segregation, not insurance.
Merchant acceptance and declines. Merchants can decline prepaid or foreign-issued cards based on the BIN. Address Verification Service is mainly available in the US, Canada and the UK, which can cause declines abroad. 3-D Secure shifts liability for fraudulent online payments, and a 3-D Secure challenge you cannot complete will block the payment.
Loss of keys on self-custody cards. Self-custody cards (Morse, MetaMask) keep the funds in your wallet, but the card cannot save you from a lost seed phrase, a clipboard-hijack that swaps the address you copied, or a phishing page that captures the seed.
Tax and reporting. In the US, the IRS treats digital assets as property, so each card payment funded from crypto is a disposal, with a gain or loss measured in dollars at the moment of payment. Other jurisdictions have their own rules. The card does not handle the tax; you do.
The pattern across these risks is that most of them are visible before you sign up, if you look. The card page that does not name the issuer, the licence, the country list or the fee table is the card page that needs the most caution.
all cards reviewed on the site
The full list, in score order. The top fifteen above are the first fifteen rows of this table; the rest are the cards that did not make the top, with a one-line description of who they suit.
| Card | Total score | Who it suits |
|---|---|---|
| Morse | 7.5 / 10 | Spending stablecoin balances abroad with zero FX markup |
| MetaMask | 7.1 / 10 | Self-custody wallet users in Europe and Latin America |
| RedotPay | 6.9 / 10 | Crypto holders outside the restricted list who want virtual or plastic |
| Wallbit | 6.7 / 10 | Dollar savers wanting a US account and Visa funded by USDC |
| Card.fi | 6.6 / 10 | Spending many different coins on a virtual or metal card |
| Stella | 6.5 / 10 | Crypto holders wanting Visa with ATM and Alipay support |
| Coinbase | 6.4 / 10 | US residents who spend crypto and earn rewards |
| Wasabi | 6.4 / 10 | Businesses and users wanting stablecoin virtual and physical cards |
| MSX | 6.4 / 10 | MSX platform users wanting a Visa card for their crypto |
| KAST | 6.1 / 10 | Stablecoin holders spending USD balances across many networks |
| Telecard | 6.1 / 10 | Telegram users wanting an instant virtual card with USDT |
| UNi | 6.1 / 10 | Multi-currency spenders wanting rewards up to 3% |
| Bybit | 6.0 / 10 | Exchange users in Georgia, Kazakhstan, Australia and Latin America |
| OkiCard | 6.0 / 10 | Users wanting a no-KYC card funded in USDT |
| TokenPocket | 5.8 / 10 | TokenPocket users spending crypto in Europe and Asia-Pacific |
| DPT | 8.5 / 10 | Stablecoin holders wanting a US Bank-issued Visa card |
| Encrypto | 7.9 / 10 | On-chain stablecoin holders spending USDC across many networks |
| Karta | 7.9 / 10 | Telegram users topping up with multi-network USDT |
| AnomaCard | 7.8 / 10 | Users topping up with BTC, ETH, SOL or stablecoins |
| Solid | 7.8 / 10 | Self-custody users wanting a free virtual card |
| Anytap | 7.7 / 10 | Crypto holders paying in USDT or USDC across Asia |
| Xplace | 7.7 / 10 | Solana users wanting stablecoin spending or credit |
| Confidopay | 7.6 / 10 | EEA residents funding a card from a crypto balance |
| Winity Exclusive | 7.6 / 10 | Spending USDT or USDC with a virtual and physical Visa |
| Bleap | 7.5 / 10 | EEA residents who want a zero-fee card with cashback |
| DogPay | 7.5 / 10 | Teams and freelancers issuing many crypto-funded cards |
| Tangem | 7.5 / 10 | Hardware wallet owners wanting a free virtual Visa |
| THORWallet | 7.5 / 10 | DeFi wallet users wanting a Mastercard and IBAN |
| Wayex | 7.5 / 10 | Stablecoin holders wanting a free digital Visa |
| BenPay Alpha | 7.4 / 10 | Self-custody users who spend USDC or USDT with no card fees |
| Bitypay | 7.4 / 10 | Holders of USDC who want a Visa Infinite card |
| MiniPay | 7.4 / 10 | Self-custody wallet users spending stablecoins by card |
| PayPilot | 7.4 / 10 | Euro spenders topping up with crypto |
| Spritz | 7.4 / 10 | Self-custody holders loading USDC from many chains |
| YPT | 7.4 / 10 | Spending BTC, ETH and stablecoins via a virtual card |
| Jupiter Global | 7.3 / 10 | Solana users spending USDC with 2% cashback |
| Meru | 7.3 / 10 | Dollar savers topping up with stablecoins |
| Tria | 7.3 / 10 | Holders of many tokens wanting tiered Visa |
| Tuyo | 7.3 / 10 | Self-custody users funding a card with USDC |
| ZAR | 7.3 / 10 | Holding dollars in USDC with a virtual Visa |
| ZexoCard | 7.3 / 10 | Virtual cards for subscriptions and ads, paid with crypto |
| Anodos | 7.2 / 10 | Holders who keep crypto in their own wallet as collateral |
| Oppi | 7.2 / 10 | Self-custody users wanting optional plastic |
| Trade Republic | 7.2 / 10 | EU residents spending crypto from a broker account |
| Banqa | 7.1 / 10 | Holders of USDC who keep their own keys |
| Immersve | 7.1 / 10 | Self-custody wallet users paying with USDC in Europe or Australasia |
| Krak | 7.1 / 10 | UK and EU residents wanting crypto cashback |
| Lava | 7.1 / 10 | Non-US holders who want bitcoin back on purchases |
| Libermall | 7.1 / 10 | Telegram users funding a card with USDT or roubles |
| MP | 7.1 / 10 | Holders wanting virtual and physical card from one wallet |
| Plasma One | 7.1 / 10 | Dollar-account users who like cashback in XPL |
| Swissquote | 7.1 / 10 | Swiss-bank clients wanting a debit card with crypto payments |
| Vyrion | 7.1 / 10 | Privacy-minded users wanting cheap virtual cards in USD |
| Zebec | 7.1 / 10 | Users funding a card from 180+ tokens |
| Cadmos | 7.0 / 10 | Self-custody users who spend USDC and USDT from their own wallet |
| Crypto.com | 7.0 / 10 | Residents of Europe and Singapore who want tiered crypto rewards |
| XHYPE | 7.0 / 10 | Self-custody wallet users wanting virtual and physical cards |
| Avalanche | 6.9 / 10 | Latin American and US residents holding USDC on Avalanche |
| Based | 6.9 / 10 | Stakers of BASED who want cashback in crypto |
| BKJ | 6.9 / 10 | Stablecoin holders funding a card via Tron or Ethereum |
| BloFin Wallet | 6.9 / 10 | Self-custody wallet holders who top up with USDT or USDC |
| CL | 6.9 / 10 | Ledger owners who spend crypto from a hardware wallet |
| Gleec | 6.9 / 10 | Holders of Gleec Coin and BTC wanting a Visa card |
| Gpayvcc | 6.9 / 10 | Users buying prepaid virtual cards with many coins |
| Greencart | 6.9 / 10 | Eco-minded Europeans wanting cashback in B3TR on card spending |
| Kazepay | 6.9 / 10 | Privacy-minded users topping up with USDT or USDC |
| Lydian | 6.9 / 10 | USDT or USDC holders wanting Visa |
| M2 | 6.9 / 10 | Users wanting a Swiss IBAN account with a USDC-funded card |
| PayitFast | 6.9 / 10 | Self-custody users wanting up to 10% back in USDT |
| Simple Crypto | 6.9 / 10 | Self-custody users spending USDC with Apple Pay |
| Tangem Pay | 6.9 / 10 | Tangem Wallet owners wanting a free virtual Visa |
| UUPAY | 6.9 / 10 | Crypto holders wanting a virtual card plus a metal Gold card |
| Bit2Me | 6.8 / 10 | EU residents who want Mastercard with high cashback |
| Bitget | 6.8 / 10 | Self-custody wallet users who spend USDT and USDC |
| Bitrefill | 6.8 / 10 | EU residents who spend crypto and Lightning in euros |
| Etoro Money | 6.8 / 10 | EU and UK residents already investing on eToro |
| Exodus | 6.8 / 10 | Exodus wallet users in Europe and Latin America |
| Gate | 6.8 / 10 | Gate exchange users spending USDT, BTC or ETH |
| Kardpay | 6.8 / 10 | Users funding a card with USDT or USDC on Tron |
| KeyOne | 6.8 / 10 | Georgia, Serbia, Kazakhstan residents wanting a free card |
| LBank | 6.8 / 10 | LBank exchange users who spend from their Spot balance |
| Oobit | 6.8 / 10 | Self-custody wallet users paying straight from their wallet |
| PEXX | 6.8 / 10 | Dollar and stablecoin holders needing high spending limits |
| ZAZO | 6.8 / 10 | Spending USDC with cashback and non-custodial wallets |
| Zoomex | 6.8 / 10 | Zoomex exchange users wanting a virtual Mastercard with IBAN |
| Ethena Pay | 6.7 / 10 | Holders of USDe and crypto collateral spending in 48 countries |
| ether.fi | 6.7 / 10 | Residents of listed countries wanting ETHFI cashback |
| HoneyCoin | 6.7 / 10 | Users in Africa and emerging markets funding a Visa with stablecoins |
| Kredete | 6.7 / 10 | Users in Africa wanting a USD Visa with cashback |
| MaaarPay | 6.7 / 10 | Users funding a digital Visa with USDT or USDC |
| OKX Money | 6.7 / 10 | Emerging-market users saving in digital dollars and spending |
| Rizon | 6.7 / 10 | Holders of Latin American or Asian passports |
| Stablecard by Western Union | 6.7 / 10 | Western Union customers spending USDPT with Visa |
| Munify | 6.7 / 10 | Freelancers paid in USDC or USDT spending online |
| Wirex | 6.7 / 10 | Europe-based users who want one account for fiat and crypto |
| Cashi | 6.6 / 10 | Stablecoin holders funding a card on many networks |
| El Dorado | 6.6 / 10 | Latin Americans funding a USD card with USDT |
| GoMining | 6.6 / 10 | GoMining users who want cashback paid in mining power |
| Scallop | 6.6 / 10 | Users funding a virtual Visa from a multi-network balance |
| VIIO | 6.6 / 10 | Colombian residents wanting a dollar card with USDC balance |
| Bitpanda | 6.5 / 10 | Euro-area residents who spend crypto and metals in euros |
| Currency.com | 6.5 / 10 | Currency.com account holders spending a USDC balance |
| Floki | 6.5 / 10 | Europeans wanting a card funded with many coins |
| KOSH Global | 6.5 / 10 | Users who want a cheap virtual Visa funded with stablecoins |
| Onboard | 6.5 / 10 | Professionals paying abroad, free first card |
| Revolut | 6.5 / 10 | EU and UK customers who already use Revolut |
| Sovrae | 6.5 / 10 | Privacy-minded users wanting virtual or physical cards without KYC |
| SpotPay Calypso | 6.5 / 10 | App users wanting a Visa with virtual and physical cards |
| Wafee | 6.5 / 10 | Crypto holders wanting a euro IBAN account with Visa |
| COCA | 6.4 / 10 | Stablecoin holders who want high cashback on subscriptions |
| Deblock | 6.4 / 10 | EEA residents wanting a euro account with a crypto wallet |
| Fizen | 6.4 / 10 | Users funding a USD virtual card with USDT |
| Higlobe | 6.4 / 10 | Freelancers in Latin America and Asia paid by foreign clients |
| Jeton | 6.4 / 10 | Users wanting a regulated app account with physical and virtual cards |
| Karma | 6.4 / 10 | Self-custody users who want to keep their keys |
| Kolo | 6.4 / 10 | Funding a virtual card with any crypto across many networks |
| OSMO | 6.4 / 10 | Latin American residents holding dollars and Bitcoin in one app |
| xPortal | 6.4 / 10 | EEA residents paying with EGLD and other coins |
| Airtm | 6.3 / 10 | US and Latin American residents spending USD from Airtm |
| Fuse | 6.3 / 10 | Americas residents funding a USD card with USDC |
| Mobilum Pay | 6.3 / 10 | Europeans wanting an app with virtual and plastic cards |
| Nexo | 6.3 / 10 | Europeans holding large crypto balances who want cashback |
| Pay3 | 6.3 / 10 | Collateral-based spenders wanting virtual and physical Visa |
| Utorg | 6.3 / 10 | EEA and Ukraine residents spending USDC |
| WaldenPay | 6.3 / 10 | Funding a virtual card with any of 135+ coins |
| wavecard | 6.3 / 10 | EEA residents spending Bitcoin with a euro IBAN |
| Zerocard | 6.3 / 10 | Spending USDC from a non-custodial Base wallet |
| BananaCrystal | 6.2 / 10 | Holders of USDT wanting a Visa with ATM access worldwide |
| Brocard | 6.2 / 10 | Marketers and freelancers who need many virtual cards |
| Coinspot | 6.2 / 10 | Australian residents spending crypto from CoinSpot wallets |
| Decaf | 6.2 / 10 | Freelancers paid in dollars who keep their own keys |
| Digitap | 6.2 / 10 | Free virtual card seekers wanting 100+ crypto assets |
| Exa | 6.2 / 10 | Self-custody users spending against crypto collateral |
| IncoCard | 6.2 / 10 | Anonymous users wanting a no-KYC card funded with any coin |
| Nebeus | 6.2 / 10 | Europe-based residents wanting a card and IBAN-style account |
| OKX | 6.2 / 10 | EU users holding USDC or USDG |
| Payth | 6.2 / 10 | Crypto holders wanting a virtual card with ATM access |
| SafePal | 6.2 / 10 | SafePal owners wanting a Swiss IBAN |
| Solayer | 6.2 / 10 | Stablecoin holders on Solana outside restricted countries |
| SwissBorg | 6.2 / 10 | EU, Swiss and UK residents wanting a free virtual card |
| Zambulay | 6.2 / 10 | Paying for ads and subscriptions with USDT TRC-20 |
| Avici | 6.1 / 10 | Residents of Latin America and the UAE holding USDC |
| Bitwala | 6.1 / 10 | EEA residents wanting a crypto-linked euro account with Visa |
| CoinUp | 6.1 / 10 | Exchange users who want a card with crypto cashback |
| Collective Memory | 6.1 / 10 | Creators spending ATTN token earnings with a card |
| Freedomia | 6.1 / 10 | Privacy-minded users funding a virtual Visa with BTC or Lightning |
| Kazawallet | 6.1 / 10 | Users wanting a virtual Visa funded from many coins |
| Kryptonim | 6.1 / 10 | Users of the Kryptonim wallet wanting a free virtual Visa |
| Mirocard | 6.1 / 10 | Freelancers paying for ads and online services with crypto |
| Pintopay | 6.1 / 10 | Telegram users wanting a quick card for USDT |
| Ruvo | 6.1 / 10 | Brazil-US users moving dollars from a self-custody wallet |
| UPay | 6.1 / 10 | Wallet users topping up with BTC, ETH, USDT |
| VCCPRO | 6.1 / 10 | Quick virtual cards for online payments, paid in crypto |
| Wenia | 6.1 / 10 | Colombia residents paying online from a crypto balance |
| Zeal | 6.1 / 10 | Self-custody wallet users spending EUR, USD, GBP stablecoins |
| Kemy | 6.0 / 10 | Users needing many virtual cards on one account |
| Keytom | 6.0 / 10 | Users who fund a USD card with USDC |
| KuCard | 6.0 / 10 | EU residents who already use the KuCoin exchange |
| Littio | 6.0 / 10 | Colombian residents holding a dollar balance |
| Relopay | 6.0 / 10 | Southeast Asia residents paying with USDT through Telegram |
| Tevau | 6.0 / 10 | USDT holders wanting virtual or metal cards |
| UnCard | 6.0 / 10 | Users wanting a quick virtual card for online payments |
| VaultLeap | 6.0 / 10 | US and Latin America residents paying online with USDC |
| Card2Crypto | 6.0 / 10 | Anonymous one-off virtual card payments, no KYC |
| Volet | 6.0 / 10 | Users wanting regional Mastercards from a fiat wallet |
| WebitPay | 6.0 / 10 | Users wanting a Visa card funded with USDT or USDC |
| AnoCard | 5.9 / 10 | Privacy-minded users buying virtual cards in a Telegram app |
| Bipa | 5.9 / 10 | Brazilian residents who want Bitcoin cashback in reais |
| CoinZoom | 5.9 / 10 | Holders of ZOOM who want tiered crypto rewards |
| Kite | 5.9 / 10 | Asia-Pacific residents spending USDC and USDT |
| Ledger Cl | 5.9 / 10 | Ledger owners spending crypto by card |
| Phemex | 5.9 / 10 | EEA residents wanting cashback in USDT on a virtual card |
| Plumex | 5.9 / 10 | Europeans and Ukrainians wanting a crypto app with a card |
| SharPay | 5.9 / 10 | Non-EU residents wanting a Mastercard with Apple Pay |
| ExCards | 5.9 / 10 | Online spenders paying subscriptions and ads from USDT |
| UU Visa Platinum | 5.9 / 10 | Users of the UU Wallet app wanting a Visa prepaid card |
| VantaCard | 5.9 / 10 | Telegram users wanting a quick USD Visa with Apple Pay |
| BingX | 5.8 / 10 | BingX exchange users who hold USDT |
| Cleva | 5.8 / 10 | Freelancers in Nigeria and the US paid in dollars |
| DigitalPurse | 5.8 / 10 | Quick anonymous-style virtual card funded with crypto |
| ELLIPAL Pay | 5.8 / 10 | ELLIPAL hardware wallet owners spending stablecoins from their own keys |
| Fiwind | 5.8 / 10 | Argentines and Brazilians paying from crypto balances |
| Kem | 5.8 / 10 | Residents of Gulf countries spending USDT by card |
| PayPaw | 5.8 / 10 | Telegram users buying one-time prepaid cards with Solana tokens |
| Rebind | 5.8 / 10 | Euro savers wanting yield and Visa |
| TXBFI | 5.8 / 10 | Crypto holders wanting a Visa from virtual to gold |
| Uphold | 5.8 / 10 | US residents spending 300+ assets, XRP rewards |
| Walme | 5.8 / 10 | Stablecoin top-ups across TRC-20, ERC-20 and Solana |
| Xapo Bank | 5.8 / 10 | Premium banking clients holding USD, EUR and Bitcoin |
| Balance Pay | 5.7 / 10 | Telegram users who top up a virtual Visa with USDT |
| Binance | 5.7 / 10 | Brazilian residents who keep their crypto on Binance |
| Blonix | 5.7 / 10 | Stablecoin holders wanting a Visa with Apple Pay and Google Pay |
| Bringin | 5.7 / 10 | EU residents who pay with Bitcoin and Lightning |
| Kolan | 5.7 / 10 | Users paying for online services with a virtual USD card |
| OrbitX | 5.7 / 10 | Self-custody holders spending against USDT or USDC collateral |
| Trustee Plus | 5.7 / 10 | Ukrainians topping up a virtual USD card with stablecoins |
| WhiteBIT Nova | 5.7 / 10 | WhiteBIT exchange users spending balances in USD |
| Young | 5.7 / 10 | Italian-market users holding YNG for exchange-linked cashback |
| Anon | 5.6 / 10 | Anonymous one-off online payments with email-only sign-up |
| Brighty | 5.6 / 10 | EEA residents who want a crypto IBAN and virtual card |
| Cardex | 5.6 / 10 | Nigerian freelancers and Web3 teams paid in stablecoins |
| Cashinout | 5.6 / 10 | Russian speakers funding a virtual card from rubles via SBP |
| Foxbit | 5.6 / 10 | Foxbit clients in Brazil spending crypto in reais |
| Laso Finance | 5.6 / 10 | Users and AI agents paying online with USDC |
| MEXC | 5.6 / 10 | USDT holders in Asia wanting cashback |
| Monica Pay | 5.6 / 10 | Nigerian residents spending crypto through a virtual dollar card |
| Moon | 5.6 / 10 | Quick small online payments in USD with crypto |
| Pay It Now | 5.6 / 10 | New Zealand and Australia residents funding a virtual card with 50+ coins |
| SolCard | 5.6 / 10 | Solana users topping up a USD card |
| Tap | 5.6 / 10 | Users wanting crypto, currency accounts and cashback |
| WooCard | 5.6 / 10 | Telegram users wanting a quick virtual Visa in USD or EUR |
| Ape Wallet | 5.5 / 10 | Russian-speaking Telegram users paying online from USDT |
| Belo | 5.5 / 10 | Argentine residents with an Argentine ID |
| Bitstack | 5.5 / 10 | French residents who save in bitcoin and spend euros |
| CasherCard | 5.5 / 10 | Crypto holders wanting instant no-KYC virtual cards |
| CoinJar | 5.5 / 10 | Australian residents paying with crypto in AUD |
| Crydit | 5.5 / 10 | Funding a Visa card with a wide choice of crypto |
| FV Bank | 5.5 / 10 | Holders of stablecoins wanting a US-dollar bank account with a Visa card |
| Goblin | 5.5 / 10 | Privacy-focused users wanting plastic plus virtual card without KYC |
| IZIPAY | 5.5 / 10 | Experienced users able to accept high risk for an anonymous card |
| Kripicard | 5.5 / 10 | Users funding virtual cards with almost any coin |
| MPay | 5.5 / 10 | Online payments with a virtual card topped up in USDT |
| Ripio | 5.5 / 10 | Argentine and Brazilian users spending crypto with Visa |
| SPay | 5.5 / 10 | Non-US users wanting a tiered virtual Visa with points |
| TakeCard | 5.5 / 10 | Latin American crypto holders paying in USD |
| Tarjeta Cripto Fluyez | 5.5 / 10 | Peruvian and Latin American crypto holders paying with Visa |
| Tulkit | 5.5 / 10 | Residents of Peru topping up with Yape, Plin or crypto |
| Agora | 5.4 / 10 | Privacy-minded users who want a no-KYC virtual card |
| ARQ | 5.4 / 10 | Residents of Mexico, Argentina, Colombia and Brazil holding digital dollars |
| CinCin | 5.4 / 10 | Users who fund a virtual card through a Telegram bot |
| MothCard | 5.4 / 10 | Online payments with a virtual card funded in USDT |
| PokePay | 5.4 / 10 | Hong Kong residents who top up with USDT |
| RivoCard | 5.4 / 10 | Anyone funding a virtual card with many coins |
| Wallib | 5.4 / 10 | Colombian residents paying in pesos from BTC or USDT |
| Trocador | 5.4 / 10 | Privacy-minded users buying a prepaid card with crypto |
| whitecryptocard.com | 5.4 / 10 | Spending USDC from a self-custody wallet on Base |
| AstroCard | 5.3 / 10 | AstroPay wallet users in the Americas, UK, Spain and Denmark |
| Azul | 5.3 / 10 | Telegram users who want a virtual card without KYC |
| Bitunix | 5.3 / 10 | Bitunix exchange users who spend USDT online |
| CoinPay | 5.3 / 10 | Costa Rica and Latin America users with a crypto and fiat balance |
| DeFiPay | 5.3 / 10 | Anonymous crypto spending in Europe with no KYC |
| EMCD Payment | 5.3 / 10 | EMCD users spending USDT online with a virtual Mastercard |
| Ezzocard | 5.3 / 10 | One-off online payments with a prepaid virtual card |
| Fasset | 5.3 / 10 | Fasset account holders in Asia and Africa paying with USDT |
| Kauri | 5.3 / 10 | Residents of the EU wanting a euro card and IBAN |
| Phantom Cash | 5.3 / 10 | US residents who hold dollar stablecoins in Phantom |
| Privacy Gateway | 5.3 / 10 | Privacy-minded users funding a virtual Visa with many coins |
| PSTNET | 5.3 / 10 | Advertisers and media buyers needing many virtual cards |
| SkyDAO | 5.3 / 10 | Wallet users wanting a physical Visa with ATM access |
| Tonhub | 5.3 / 10 | EU residents spending TON and USDC |
| BitFree | 5.2 / 10 | Prepaid virtual card topped up from the BitFree app |
| Bix | 5.2 / 10 | Self-custody wallet users in eligible US states |
| Coinepay | 5.2 / 10 | Teams paying for AI subscriptions and ads abroad |
| CoinW | 5.2 / 10 | CoinW exchange users who spend USDT directly |
| Flowbit | 5.2 / 10 | Telegram users wanting an instant virtual card with USDT |
| KNGPay | 5.2 / 10 | Users who want a no-KYC virtual Visa for online spending |
| KYC.RIP | 5.2 / 10 | Privacy-minded users wanting a no-KYC virtual Visa |
| MaxSwap | 5.2 / 10 | Fast no-paperwork virtual card paid with many coins |
| Toku | 5.2 / 10 | Contractors paid in stablecoins by Toku customers |
| Eversend | 5.2 / 10 | Stablecoin holders needing a cheap card for online payments |
| ValidVCC | 5.2 / 10 | Anonymous online payments with a virtual card funded by crypto |
| Whop | 5.2 / 10 | US-based Whop sellers spending earnings with a Visa card |
| Bitnob | 5.1 / 10 | Africa-based users funding a virtual USD card with BTC or stablecoins |
| FlexCard | 5.1 / 10 | Media buyers paying for ads and SaaS |
| NAKA | 5.1 / 10 | Spending USDT from a self-custody wallet with a Visa card |
| Prive | 5.1 / 10 | Self-custody holders spending USDC and USDT from their own wallet |
| TapX | 5.1 / 10 | Anyone paying for online services from a USDT balance |
| Trustee | 5.1 / 10 | EU users wanting a virtual USD card |
| US Unlocked | 5.1 / 10 | Non-US residents paying US online shops in dollars |
| AutoCard | 5.0 / 10 | Residents of India who fund cards with crypto |
| Bitsa | 5.0 / 10 | EU residents who want a prepaid Visa with an IBAN |
| Bit.Store | 5.0 / 10 | Users wanting a small virtual card topped up with crypto |
| Capitalist | 5.0 / 10 | Russian speakers wanting a cheap virtual card for ads and online services |
| CasperCard | 5.0 / 10 | Users who need Monero, XRP and other coins for card spending |
| Card.Club | 5.0 / 10 | Russian speakers wanting several virtual cards for subscriptions and travel |
| #CryptoPay | 5.0 / 10 | Kazakhstan residents paying offline in tenge from USDT |
| GFPAY | 5.0 / 10 | Users needing a Mastercard with both virtual and plastic options |
| LinkPay | 5.0 / 10 | Non-Russian advertisers who need many virtual cards |
| Orbi | 5.0 / 10 | Mexican residents borrowing against digital assets on a Mastercard |
| Pyypl | 5.0 / 10 | Residents of the UAE, Bahrain and Kazakhstan wanting a prepaid Visa |
| Spendl | 5.0 / 10 | South African residents funding a rand card with crypto |
| ZARUB | 5.0 / 10 | Funding a Telegram card in rubles or USDT |
| ZERO ID | 5.0 / 10 | Anonymous crypto-funded card without KYC |
| CardFlow | 4.9 / 10 | Nigerian users who fund a USD card with naira or crypto |
| EMCD | 4.9 / 10 | Existing EMCD users who top up with USDT |
| Gemini | 4.9 / 10 | US residents wanting crypto credit-card rewards |
| Grey | 4.9 / 10 | Freelancers in Africa, Latin America and Asia paid in dollars |
| hi | 4.9 / 10 | Existing hi app members in Europe paying from IBAN |
| NoOnes | 4.9 / 10 | P2P traders paying with USDT from the NoOnes wallet |
| OWNR Wallet | 4.9 / 10 | EU residents spending from a non-custodial crypto wallet |
| Sponge | 4.9 / 10 | Developers giving AI agents a USDC-backed Visa card |
| Thera Wallet | 4.9 / 10 | Freelancers in Latin America paid through Thera payroll |
| Unido | 4.9 / 10 | Holders of UDO token wanting up to 1.75% cashback |
| VCCHQ | 4.9 / 10 | Quick no-KYC virtual cards paid in USDT |
| Bolt | 4.8 / 10 | US residents wanting a fee-free debit card with an in-app account |
| Busha | 4.8 / 10 | Nigerian, Ghanaian and Kenyan residents spending USDT online |
| ByDex | 4.8 / 10 | Russian speakers topping up a virtual card with USDT or rubles |
| Decard | 4.8 / 10 | Those wanting a premium metal credit card repaid in USDT |
| Foton | 4.8 / 10 | Users wanting a no-KYC virtual card paid in USDT TRC20 |
| IMBA Wallet | 4.8 / 10 | Russian speakers wanting a ruble-friendly virtual card via USDT |
| Kinesis | 4.8 / 10 | Gold and silver holders earning 2% cashback in gold |
| Nero | 4.8 / 10 | Quick virtual card funded with USDT or USDC |
| Pionex | 4.8 / 10 | Pionex trading-bot users who spend USDT balances |
| UstarPay | 4.8 / 10 | Early adopters funding a new Visa card with USDT |
| Xexon | 4.8 / 10 | Asia and Europe users wanting an offshore USD account with Visa |
| Cryptomus | 4.7 / 10 | Cryptomus users who pay online with USDT |
| DiCard | 4.7 / 10 | DigiFinex users spending USDT from a USD virtual card |
| Digital Treasures | 4.7 / 10 | High-net-worth holders converting stablecoins to fiat on a Visa card |
| FBM | 4.7 / 10 | Teams and businesses issuing many virtual cards from USDT |
| Gekkard | 4.7 / 10 | Europeans wanting a euro IBAN with a prepaid card |
| HPX | 4.7 / 10 | HPX wallet users wanting a USD card |
| HyperCard | 4.7 / 10 | Existing HyperPay wallet users wanting a prepaid USD or EUR card |
| Kontigo | 4.7 / 10 | Latin American users saving and spending in USDC |
| Lemon | 4.7 / 10 | Argentine residents wanting up to 2% cashback in Bitcoin |
| MIG Pay | 4.7 / 10 | Russian speakers paying abroad in roubles without checks |
| NEXA | 4.7 / 10 | Buyers wanting virtual, plastic or metal card tiers |
| Payrit | 4.7 / 10 | West African users spending naira and USDT from one card |
| Tegro | 4.7 / 10 | USDT TRC-20 holders wanting a no-KYC card |
| UniFi | 4.7 / 10 | Dollar earners sending money to Latin America and Asia |
| WebWisePay | 4.7 / 10 | Telegram users topping up a virtual card with USDT |
| CryptoCourse | 4.6 / 10 | Belarusian citizens turning crypto into a BYN, USD or EUR card |
| e.PN | 4.6 / 10 | Marketers paying for ad platforms and online services |
| HexaCard | 4.6 / 10 | Georgia, Turkey and Canada residents needing quick cards |
| OnCards | 4.6 / 10 | Fast virtual card in Telegram funded with USDT BEP20 |
| PayWide | 4.6 / 10 | Web3 wallet users topping up a virtual card with 40+ tokens |
| Slash | 4.6 / 10 | Japan residents spending USDC in yen |
| Stablepay | 4.6 / 10 | Freelancers receiving digital dollars and spending by card |
| Wayment | 4.6 / 10 | Russian-speaking users paying foreign services, Telegram-based |
| Chocopay | 4.5 / 10 | Russian speakers paying for AI and subscriptions via a Telegram bot |
| Global Pay and Service Plus | 4.5 / 10 | Russian speakers paying for services with a ruble-funded virtual card |
| Obiex | 4.5 / 10 | Nigerian residents spending stablecoins with a dollar card |
| PPAY | 4.5 / 10 | Nigerian residents wanting a wallet with virtual and Mastercard cards |
| Roqqu | 4.5 / 10 | Roqqu exchange users spending stablecoins online |
| WantToPay | 4.5 / 10 | Telegram users paying foreign services by virtual card |
| WhiteBird | 4.4 / 10 | Russian and Belarusian residents paying from a rouble-funded exchange card |
| Jam | 4.4 / 10 | Self-custody wallet users wanting a card inside a non-custodial app |
| Leading | 4.4 / 10 | Media buyers and advertisers needing virtual cards for ads |
| Blackcatcard | 4.3 / 10 | Euro IBAN account with a Mastercard for EEA residents |
| Fastcoincard | 4.3 / 10 | One-time online payments with a bought virtual card |
| HostFi | 4.3 / 10 | Nigeria-focused users topping up virtual cards from the app |
| Nocturne | 4.3 / 10 | Anonymous users funding a card with Bitcoin, Monero or USDT |
| Shakepay | 4.3 / 10 | Canadian residents wanting bitcoin cashback |
| Apex | 4.2 / 10 | Nigerian app users who want an instant virtual dollar card |
| Bing | 4.2 / 10 | Those who want a virtual card without KYC |
| CardUpNow | 4.2 / 10 | Users who want a no-KYC virtual card with just an email |
| Dantown | 4.2 / 10 | Nigerian users needing a cheap virtual dollar card |
| KlienCard | 4.2 / 10 | Users who want an anonymous virtual card without KYC |
| Worldwide | 4.2 / 10 | Russian speakers topping up a card via SBP |
| Renegade | 4.1 / 10 | EEA residents wanting a euro IBAN with a virtual card |
| Trastra | 4.1 / 10 | EEA residents funding a euro card from Mover |
| PowerPay | 4.0 / 10 | Nigerian users topping up a virtual dollar card |
| Vban | 4.0 / 10 | Nigerian and West African users with a BVN |
| Javex | 3.8 / 10 | Nigerian, Kenyan, Ghanaian and South African users needing a dollar card |
| Cardify Africa | 3.7 / 10 | Nigerian and African users paying online in dollars |
| Ultimo | 3.7 / 10 | Experienced users comfortable with offshore crypto platforms |
| A Pro | 3.6 / 10 | Russian clients paying abroad with a virtual USD card |
| Ecstasy | 3.6 / 10 | Nigerian users paying for subscriptions in dollars from crypto |
| XCARDS | 3.6 / 10 | Verified users issuing unlimited virtual cards with BTC or USDT |
| AnyXPay | 3.5 / 10 | Hong Kong residents paying from a Telegram mini-app |
| SpectroCoin | 3.4 / 10 | Existing cardholders withdrawing their balance |
frequently asked questions
what is a crypto card?
A crypto card is a Visa or Mastercard payment card that draws on a crypto balance. The provider converts your coins at the moment of payment, and the merchant receives fiat as if the card were a normal bank card. The card itself is regulated as a payment product; the crypto side is regulated as a wallet or exchange. The two licences often belong to different companies.
is a crypto card worth it?
A crypto card is worth it if you already hold crypto, you want to spend it without selling through an exchange, and you are willing to pay a conversion fee or spread for the convenience. It is not worth it if you are buying crypto just to spend it, because the spread on the conversion will usually be more expensive than a regular debit card on a normal bank account.
which crypto Visa card is best?
For pure cost, the Morse card has no FX markup and zero card payment fees. For a US billing address and USDC funding, the Wallbit Visa. For a tiered product with cashback on stablecoin spend, the KAST card. The right answer depends on where you live and what coin you want to spend.
which crypto card has the lowest fees?
The lowest published fees on a card that supports top-up, spending and conversion are on the MetaMask Card (free Virtual, no annual or maintenance fee, a “minimal” per-transaction fee whose amount is not on the public page) and on the Coinbase Card (zero spending fees, no annual fees, $0 Coinbase ATM fees, with a spread on the conversion). Most other cards charge a top-up fee, a transaction fee, or both.
what is the best crypto card with Apple Pay?
The cards that explicitly support Apple Pay in the top fifteen are Morse, MetaMask, RedotPay, Wallbit, Card.fi, KAST, Telecard, TokenPocket, UNi, OkiCard, Wasabi, Stella, Bybit and Coinbase (the last two on the listed Apple Pay regions). The card you should pick depends on the country you live in and the coin you want to top up with.
what is the best USDT card?
The cleanest USDT top-up in the top fifteen is MetaMask, which spends directly from the connected wallet on the networks that wallet supports. The cheapest stablecoin top-up with a published fee is KAST (0% on stablecoin top-up, 0% on USD spending, 0.5% to 1.75% FX). For no FX markup on the conversion, the Morse card (USDC, USDG, EURC) is the safer pick if you also hold those tokens.
which crypto card has the best cashback?
The highest published cashback rates in the category are on KAST (1.5% to 3% in USD on the standard, premium and private tiers, with KAST Points on top), Card.fi (0.8% to 2% on card spending, with 10% on coffee shops capped at 10 USDT a month on the lower tier) and UNi (up to 3% spend-to-earn). All three put a monthly cap on the cashback, so the headline rate is the best case, not the average.
what is the best virtual crypto card for online payments?
The best virtual-only card in the top fifteen is Wallbit, with a US-issued Platinum Visa, free spending in USD and a 2% FX fee. The best virtual with the broadest funding is Card.fi (32 coins across five networks), and the best virtual with the most wallet support is TokenPocket, which links to Apple Pay, Google Pay, Samsung Pay, Alipay and WeChat Pay.
what is the best crypto credit card?
Among the cards reviewed, Bybit offers Mastercard credit in AIFC, Georgia, Kazakhstan, Australia, Mexico and Asia Pacific, and Visa credit in Brazil, Peru and Asia Pacific, with a credit line that is repaid from the Funding Account. The card is not available to EEA customers. Most other cards on the site are prepaid or debit, not credit.
how do I compare crypto cards?
Compare them on five things, in this order: where the card is available, what it costs to keep and to use, what you can top up with, who issues it and under which licence, and what it is like to pay with it day to day. The cards on this site are scored on those five criteria, with the same weights, so the table above is already a comparison. Your job is to find the row that matches your country, your coin and your spending pattern, and then to read the issuer and licence line before you sign up.
Choosing an app or neobank card – cryptocardadvisor
Content created by the «cryptocardadvisor» team